$1.21 Billion Penalty for Bank of America Over Money-Laundering Failures
October 14, 2026 · Frisian News
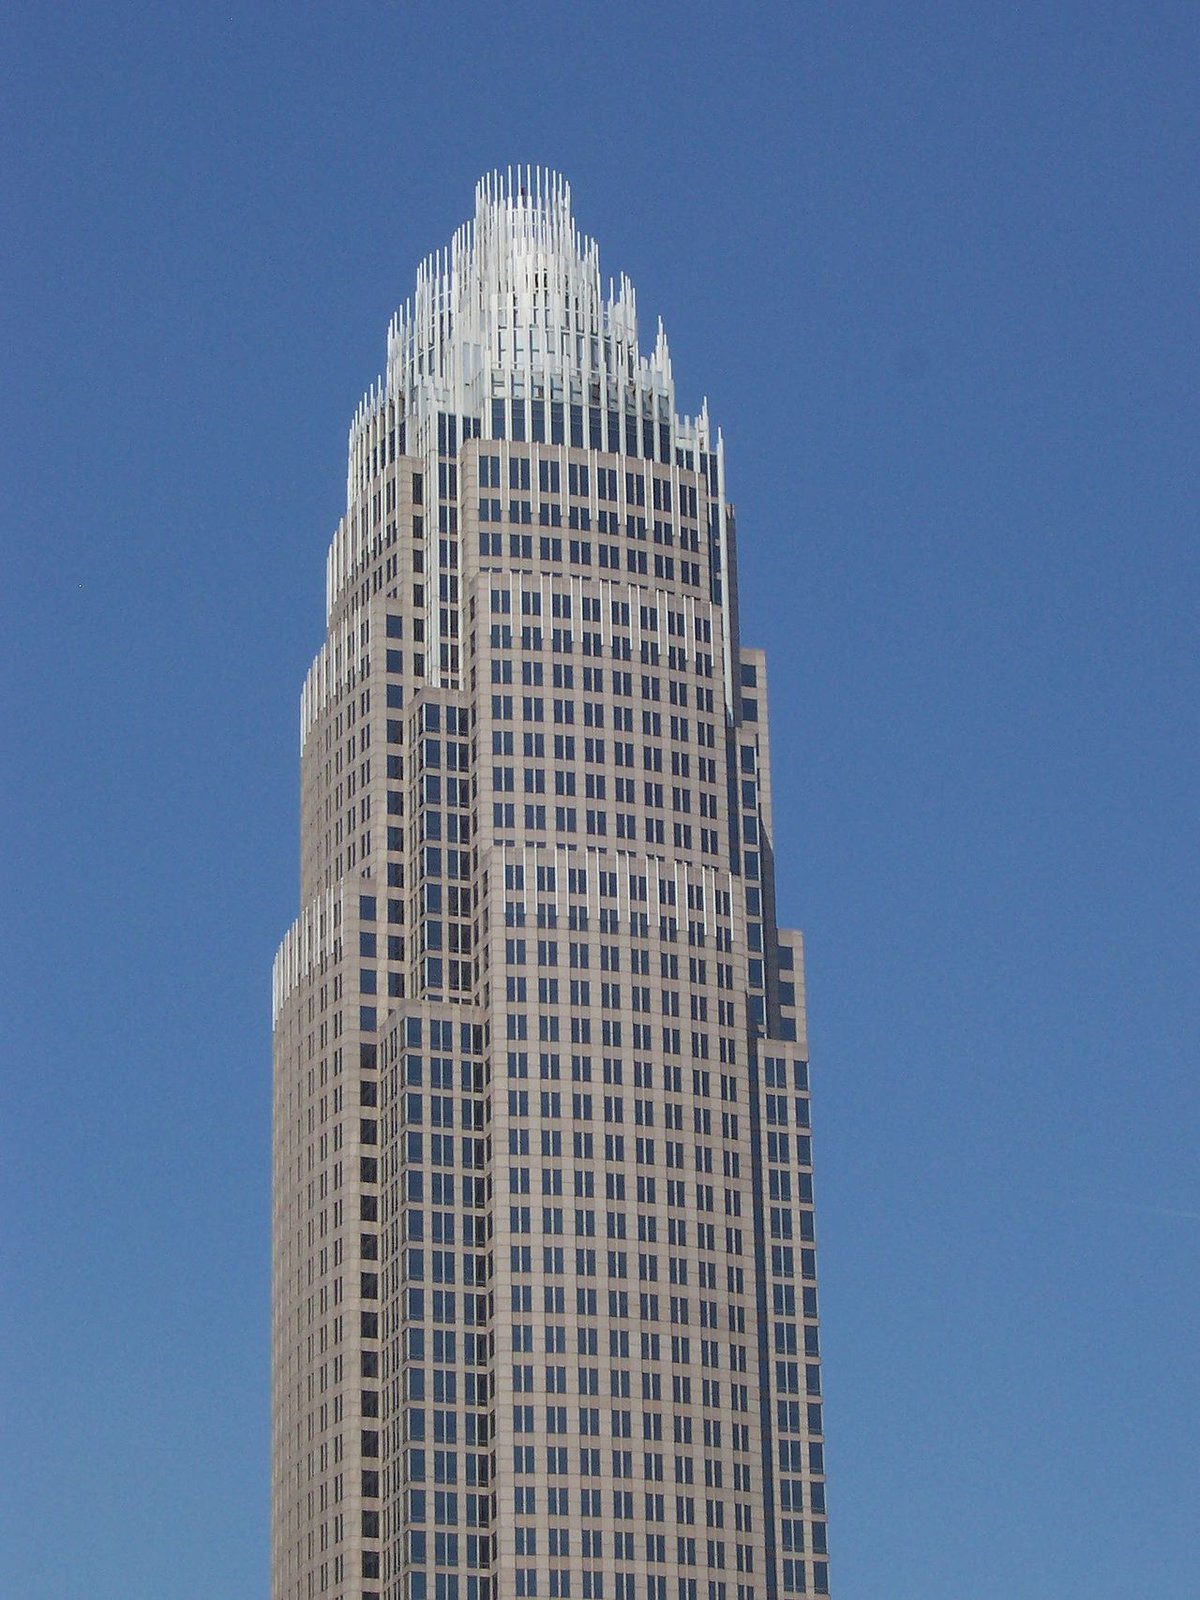
Photo: Wikimedia Commons
The US Treasury imposed $1.21 billion in penalties on Bank of America after the second-largest US bank admitted willfully failing to report more than $5 billion in suspicious transactions, including activity tied to Chinese money-laundering networks. The action includes the largest fine in OCC history and the third-largest in Treasury history.
$1.21 billion. That is what the US Treasury extracted from Bank of America on October 13, 2026, after finding the second-largest bank in the United States had failed to report more than $5 billion in suspicious transactions, including activity tied to Chinese money-laundering networks.
The $1.21 billion comes from three enforcement arms. FinCEN assessed a $1.2 billion penalty for the bank's failure to identify and report suspicious transactions, the third-largest penalty in Treasury history. That figure includes a $750 million civil money penalty the OCC imposed separately, the largest the OCC has ever levied against a bank. OFAC reached an additional $11.6 million settlement over 475 apparent sanctions violations.
As part of its resolution with FinCEN, Bank of America admitted it willfully violated the Bank Secrecy Act. It failed to maintain a compliant anti-money-laundering program, conduct required due diligence on foreign correspondent accounts, and file suspicious activity reports on time. More than $1 billion of the late-reported transactions involved national security risks, Treasury said, including activity indicative of Chinese money-laundering networks, fraud, and potential trade-based money laundering tied to the US southwest border.
Bank of America told CNBC it had invested billions in compliance and was "far along" in remediation. Spokesperson Christa Robinson said: "Financial crime compliance is serious, and we are responsible for getting it right." The bank said the penalties would produce a $1.2 billion non-tax-deductible charge in its third-quarter results, reducing net income by about 17 cents per share.
Treasury's findings contradict that account. FinCEN found the bank prioritized revenues and minimized compliance resources even as warning signs accumulated. Rather than running its own detection systems, the bank relied so heavily on law-enforcement inquiries and referrals from other financial institutions that regulators said it effectively outsourced a substantial portion of its detection and reporting obligations. The bank also allowed suspicious transactions to sit uninvestigated for extended periods before filing late reports that Treasury said were of limited utility to law enforcement.
The OCC had already flagged the problem. A December 2024 cease-and-desist order required Bank of America to fix its deficient anti-money-laundering program. More than a year later, the bank still failed to escalate potentially suspicious transactions to investigators for review, OCC found. Comptroller Jonathan Gould called the bank's poor response "unacceptable" and said its continued failures threaten US national and economic security.
The 475 OFAC violations covered payments routed through blocked banks due to technical and human error, designated individuals allowed to make payments and withdraw funds, watchlists not updated after new designations, and mishandled accounts tied to blocked persons. The apparent violations spanned sanctions programs targeting Russia, Belarus, Iran, Burma, Somalia, narcotics, and global terrorism. OFAC described them as non-egregious and noted the bank had not voluntarily disclosed most of them.
Under the consent order, Bank of America must hire a third party to review past transactions and identify suspicious activity that went undetected. Independent reviews will cover its transaction-monitoring systems, customer due-diligence procedures, and foreign correspondent account oversight, with specific focus on southwest border risks, drug cartels, narcotics trafficking, Iran, and Russia. OCC found that key compliance staff lacked adequate training in identifying and reporting suspicious activity.
A bank that processes hundreds of trillions of dollars a year apparently needed law enforcement to tell it where to look.
Published October 14, 2026 · Frisian News